Finding the right and affordable car insurance in New York City in 2026 is not always easy. There are many insurance companies offering different policies, coverage options, discounts, and prices, so it can be confusing to figure out which one is actually best for you.
Two people living in New York can get completely different car insurance quotes even if they drive similar vehicles. Your age, ZIP code, driving history, vehicle, coverage level, and other personal factors can all affect how much you pay.
That is why the cheapest insurance company for one driver may not be the cheapest for another.
In this guide, we will look at some well-known car insurance companies in New York, the state’s legal minimum insurance requirements, why prices can be different for different drivers, and practical ways you can potentially lower your car insurance costs.
The main thing I want you to remember is this: cheap does not always mean best. You want a policy that gives you reasonable protection at a price you can afford.
Best Car Insurance Companies in New York in 2026
Several major insurance companies are competing in New York in 2026. Forbes Advisor recently evaluated 16 major car insurance companies in the state, looking at rates for different driver profiles, driving records, accidents, speeding tickets, and complaint data.
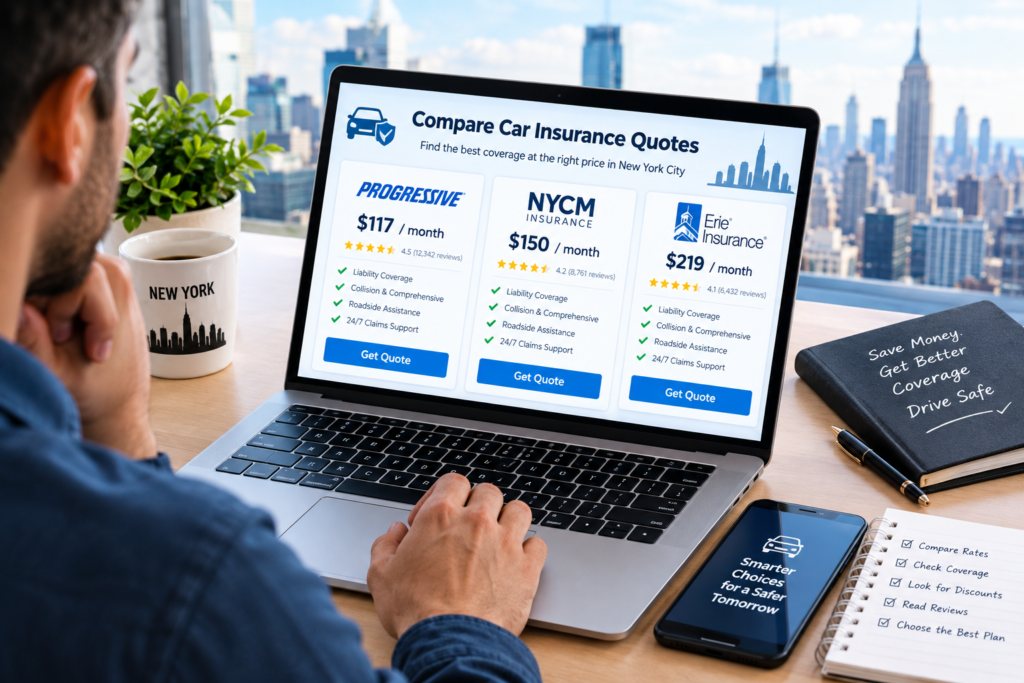
Among its top picks were NYCM Insurance, Erie, and Progressive.
NYCM Insurance
NYCM Insurance received a 5.0 Forbes Advisor rating in the 2026 New York analysis and had a very low complaint level.
For a good driver, Forbes lists an average monthly rate of about $150 in New York.
NYCM may be worth considering if you care about both price and customer service. However, it is available only in New York, and you need to contact an agent to get a quote and purchase a policy.
Erie Insurance
Erie is another highly rated option in New York.
Forbes lists an average monthly rate of about $219 for a good driver in New York and reports a very low complaint level. Erie also received strong marks for claims handling in the Forbes analysis.
That can make Erie interesting for drivers who care about more than simply getting the lowest possible premium.
Progressive
Progressive is another major option to consider.
Forbes lists an average monthly rate of about $117 for a good driver in New York, making it the lowest of these three companies in that particular comparison. Progressive also had a low complaint level.
Progressive may also be worth looking at if you have certain driving problems on your record. In the Forbes analysis, it was highlighted for drivers who caused an accident involving an injury.
Important: These Are Not NYC Guaranteed Prices
There is something very important you should understand before looking at these numbers.
These are average New York State rates, not guaranteed prices for everyone living in New York City.
Your actual quote can be completely different.
For example, two drivers living in different parts of NYC can receive different prices because insurers consider factors such as location, driving history, vehicle, age, coverage, and other rating information.
So don’t look at a $117 or $150 average and assume that is exactly what you will pay.
The only way to know your actual price is to get a personalized quote.
What Makes an Insurance Company the Best?
When you are buying car insurance, looking only at the monthly price is not enough.
Let’s say one company is $30 cheaper per month than another company. That sounds great at first.
But what happens if you have an accident and discover that the cheaper policy does not provide the level of protection you actually need?
On the other hand, another company might cost a little more but offer better coverage options, better claims handling, or stronger customer service.
In that situation, paying a little more could make sense.
When comparing car insurance companies, I would look at these things:
- Monthly and annual premium
- Liability coverage limits
- Deductible
- Collision coverage
- Comprehensive coverage
- Uninsured motorist coverage
- Customer complaints
- Claims process
- Available discounts
- Overall financial protection
For example, if one company costs $10, $20, or even $50 more per month but gives you significantly better protection, don’t automatically reject it just because it is more expensive.
My advice is simple: compare the price, but also compare what you are actually getting for that price.
New York Car Insurance Requirements in 2026
If you drive a vehicle in New York, you are required to carry certain minimum levels of auto insurance.
According to the New York Department of Financial Services, the state’s minimum liability limits are generally:
- $25,000 for bodily injury to one person
- $50,000 for bodily injury to two or more people in one accident
- $10,000 for property damage in one accident
These limits are commonly referred to as 25/50/10.
New York also requires Personal Injury Protection, commonly called PIP, because New York is a no-fault auto insurance state.
Uninsured motorists coverage is also required. The New York Department of Financial Services says the required uninsured motorists coverage provides up to $25,000 for one person and $50,000 for two or more people in one accident.
But remember, these are legal minimums.
That does not necessarily mean they are enough for your personal financial situation.
Is New York’s Minimum Car Insurance Enough?
This is where you need to think carefully.
Yes, you can buy the legal minimum coverage, but minimum coverage does not automatically mean you have complete financial protection.
Imagine that you cause a serious accident and the total damages are greater than your policy limits.
Your insurance may pay up to the limits of your policy, but you could potentially still be responsible for costs above those limits.
That is one reason some drivers choose higher liability limits than the legal minimum.
For example, Forbes Advisor’s New York rate comparisons use 100/300/100 liability limits for its standard comparison rather than the state’s minimum limits.
That does not mean every New York driver needs exactly 100/300/100 coverage.
Your appropriate coverage depends on your financial situation, assets, vehicle, risk tolerance, and other personal factors.
If you are unsure, talking with a licensed insurance agent can help you understand how much coverage makes sense for you.
Minimum Coverage vs. Full Coverage Car Insurance
A lot of people hear the term “full coverage” and assume it means their vehicle is protected against absolutely everything.
That is not how it works.
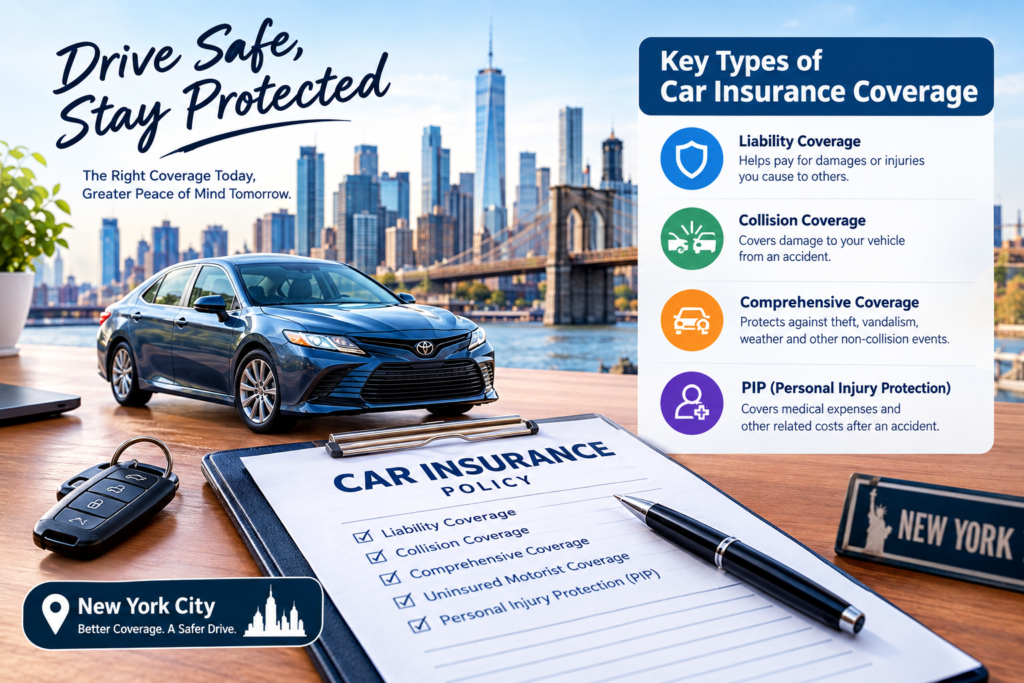
“Full coverage” is not one specific policy that automatically covers every possible loss. It commonly refers to a policy that combines liability coverage with collision and comprehensive coverage.
What Is Collision Coverage?
Collision coverage can help pay to repair or replace your vehicle after a covered collision, subject to your deductible and policy terms.
For example, if your car is damaged in a covered crash, collision coverage may help with the cost of repairing your vehicle.
What Is Comprehensive Coverage?
Comprehensive coverage can help cover certain types of damage that are not caused by a collision.
Depending on the policy, this can include situations such as theft, vandalism, falling objects, or certain weather-related damage.
So if someone tells you that “full coverage covers everything,” don’t simply accept that statement.
Always check the actual policy, coverage limits, exclusions, and deductible.
If your vehicle is financed or leased, your lender or leasing company may also require collision and comprehensive coverage.
What Is the Best Car Insurance in NYC?
This is probably one of the most common questions people ask:
Which car insurance company is the best in New York City?
The honest answer is that there is no single company that is automatically the best for every driver.
For one driver, Progressive may offer the best price.
For another driver, NYCM may be a better option.
Someone else may find that Erie offers the coverage and service they prefer.
Forbes Advisor’s 2026 New York analysis also shows that different companies can be better for different driver profiles. For example, Progressive was listed as the best option among its picks for good drivers and drivers with speeding tickets, while NYCM was highlighted for drivers with poor credit.
This is exactly why I would not recommend choosing an insurance company based only on a list you found online.
Instead, get quotes from several companies and compare them.
Look at the price, but also look at:
- Coverage limits
- Deductibles
- Discounts
- Customer complaints
- Claims experience
- Additional coverage options
Then choose the policy that gives you the combination of price and protection that makes sense for you.
Why Car Insurance Prices Are Different in NYC
You may wonder why your friend pays $150 per month while another person pays $250 or $300 for car insurance.
There is no single reason.
Insurance companies use different methods to calculate risk and set premiums. Your location, driving history, age, vehicle, coverage choices, and other factors can affect the final price.
Your driving record is particularly important.
A clean driving record can help you qualify for better rates, while speeding tickets, accidents, or other violations can increase your premium.
The type of vehicle you drive can also matter.
A newer or more expensive vehicle can have different insurance costs than an older, less expensive vehicle.
And living in New York City can make the situation even more complicated because traffic, population density, theft risk, parking conditions, and accident frequency can vary between areas.
How to Find Cheap Car Insurance in NYC
If your main goal is to save money, don’t simply choose the first insurance company that gives you a quote.
Instead, try these steps.
1. Compare Quotes From Multiple Companies
This is probably the most important step.
Get quotes from several insurers and compare similar coverage levels.
A company that is expensive for one driver could be surprisingly cheap for another.
Forbes Advisor also recommends comparing rates from multiple insurers because companies use different methods to calculate risk and prices.
2. Ask About Discounts
Many insurance companies offer discounts depending on your situation.
Depending on the insurer, discounts may be available for things such as:
- Safe driving
- Multiple policies
- Multiple vehicles
- Certain safety features
- Paying the premium in a particular way
- Completing eligible driver programs
Ask the insurer which discounts you qualify for rather than assuming there are none.
3. Choose Your Deductible Carefully
A higher deductible can sometimes reduce your premium.
But remember: if you have a claim, you may have to pay more out of pocket before the insurance company pays its portion.
So don’t choose a deductible that you cannot comfortably afford.
4. Review Your Coverage
Don’t pay for coverage you don’t need, but don’t remove important protection just to save a few dollars.
The goal should be to find the right balance between affordability and protection.
5. Keep a Clean Driving Record
A clean driving history can help you get better insurance rates.
Speeding tickets and accidents can make insurance more expensive, so safe driving is one of the simplest long-term ways to protect your insurance costs.
Don’t Choose Car Insurance Based Only on Price
I know the title of this article is about finding cheap car insurance.
But there is something I really want to make clear.
The cheapest policy is not always the best policy.
If you save $30 a month but end up with inadequate protection after a major accident, that monthly saving may not be worth it.
Think about it this way.
You are not buying car insurance because you expect to have an accident tomorrow.
You are buying it because you want financial protection if something unexpected happens.
So when you compare insurance companies, ask yourself:
What am I getting for the price I am paying?
That question is much more useful than simply asking:
Which company is the cheapest?
Final Thoughts
If you are searching for the best and cheapest car insurance in NYC in 2026, don’t make your decision based on price alone.
Companies such as NYCM Insurance, Erie, and Progressive are among the insurers highlighted in Forbes Advisor’s 2026 New York analysis, but the best option for you depends on your individual driver profile and the quote you receive.
Remember that the average rates you see online are not a guarantee of what you will personally pay.
Your age, location, vehicle, driving history, coverage limits, deductible, and other factors can all affect your final premium.
That’s why my advice is to get quotes from at least three or four insurance companies and compare them carefully.
Don’t just compare the monthly payment.
Look at the coverage limits, deductibles, discounts, claims process, customer complaints, and the protection you are actually receiving.
At the end of the day, the best car insurance policy is not necessarily the one with the lowest price.
It is the policy that gives you the protection you actually need at a price you can reasonably afford.